Maximize 2026 Financial Aid: College Students’ Guide to Extra $1,500
Maximize Your 2026 Financial Aid: A Step-by-Step Guide for US College Students to Secure an Extra $1,500
For many aspiring college students in the United States, the dream of higher education is often accompanied by the daunting reality of its cost. Tuition fees, housing, textbooks, and living expenses can quickly accumulate, making financial aid a crucial lifeline. As we look towards the 2026 academic year, understanding how to effectively maximize financial aid can be the difference between a manageable college experience and one fraught with financial stress. This comprehensive guide is designed to equip US college students with the knowledge and strategies to not only navigate the complex world of financial aid but also to potentially secure an additional $1,500 or more in funding.
The journey to securing adequate financial assistance is multifaceted, involving a combination of federal, state, institutional, and private resources. It requires proactive planning, meticulous attention to detail, and a thorough understanding of the various aid programs available. Our goal here is to demystify this process, providing actionable steps and insights that can significantly impact your financial aid package for 2026. From mastering the FAFSA to uncovering hidden scholarship opportunities, we’ll cover everything you need to know to boost your eligibility and alleviate the financial burden of college.
Securing an extra $1,500 might seem like a modest goal, but in the context of college expenses, it can cover the cost of textbooks for a semester, a significant portion of living expenses, or even a flight home during breaks. Every dollar counts, and with the right approach, students can unlock financial resources they might not have even known existed. Let’s dive into the practical solutions and financial impacts of maximizing your financial aid.
Understanding the Foundation: The FAFSA and CSS Profile for 2026
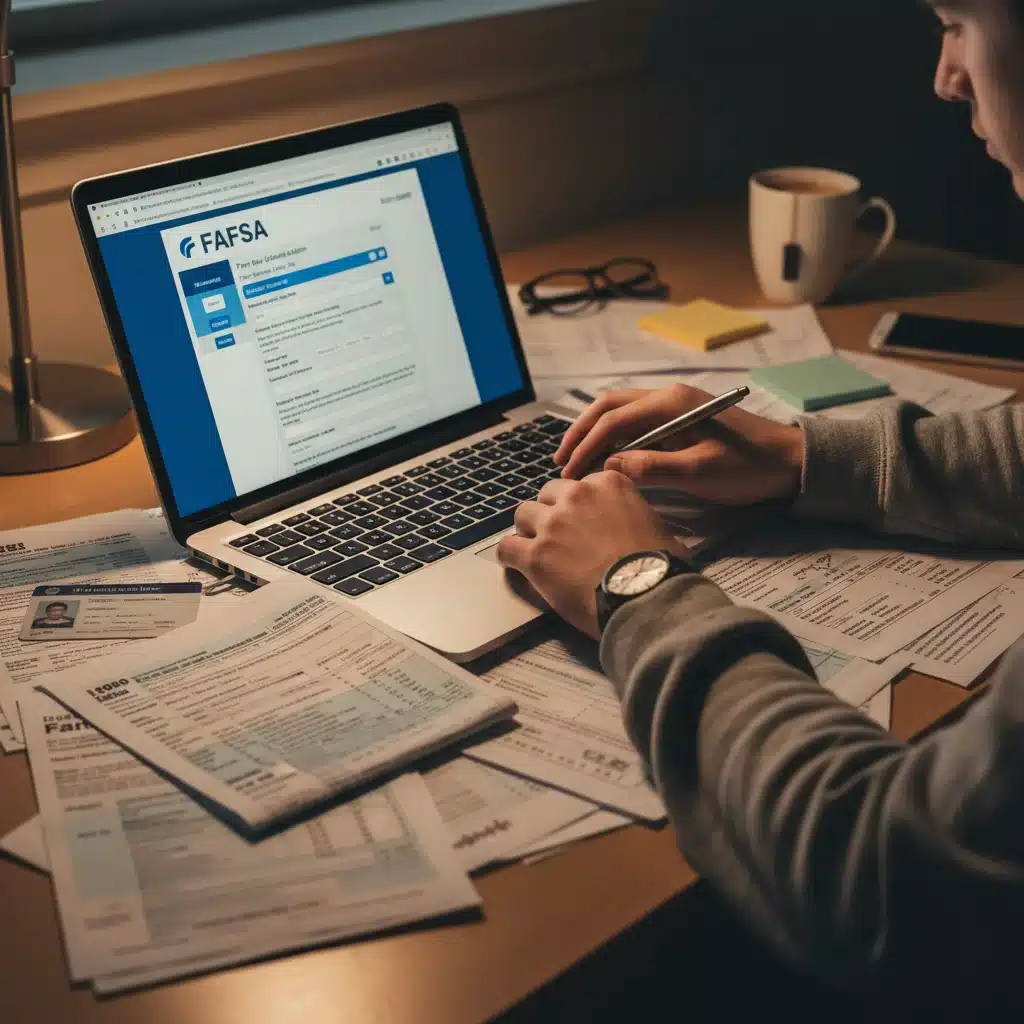
The Free Application for Federal Student Aid (FAFSA) remains the cornerstone of financial aid for most US college students. It’s the gateway to federal grants, work-study programs, and federal student loans. For the 2026 academic year, the FAFSA will be available starting October 1, 2025. Filing it as early as possible is paramount. Why? Because some aid is awarded on a first-come, first-served basis, and state and institutional deadlines often precede the federal deadline. Missing these crucial dates can mean missing out on significant funding.
FAFSA: Your First and Most Important Step
The FAFSA collects information about your family’s financial situation to determine your Expected Family Contribution (EFC). This EFC, now being replaced by the Student Aid Index (SAI) for the 2024-2025 award year and beyond, is a crucial number that colleges use to calculate your financial need. For the 2026-2027 FAFSA, you will use your family’s 2024 tax information. This is a critical detail that many students and parents overlook, leading to delays or errors.
- Gather Your Documents Early: Before the FAFSA even opens, start gathering necessary documents. This includes your (and your parents’, if you’re a dependent student) 2024 tax returns, W-2 forms, and records of any untaxed income. Also, have records of cash, savings, checking account balances, and investments readily available.
- Create an FSA ID: Both the student and one parent (if dependent) need an FSA ID to sign the FAFSA electronically. This is your digital signature and can take a few days to process, so create it well in advance.
- File Early and Accurately: As mentioned, early submission is key. Double-check all information before submitting. Errors can delay processing and potentially reduce your aid eligibility. If you need to make corrections later, you can, but it’s best to get it right the first time.
- List All Potential Schools: You can list up to 10 schools on your FAFSA. Even if you’re not sure you’ll apply to a particular institution, include it. You can always remove schools later, but adding them after submission can sometimes be a hassle.
- Understand the SAI: The new Student Aid Index (SAI) is a significant change. Unlike the EFC, the SAI can be a negative number, indicating a higher level of financial need. Familiarize yourself with how the SAI is calculated and what factors influence it. This understanding can help you strategically plan your finances.
The CSS Profile: For Institutions with Additional Aid
While the FAFSA is used by all schools to determine federal aid, some private colleges and universities also require the CSS Profile (College Scholarship Service Profile). This form collects more detailed financial information than the FAFSA, giving institutions a more comprehensive picture of your family’s ability to pay. The CSS Profile also typically opens on October 1st for the following academic year.
- Check School Requirements: Not all schools require the CSS Profile. Check the financial aid websites of each college you’re applying to to see if it’s a requirement.
- Be Prepared for More Detail: The CSS Profile asks for information on home equity, small business values, and non-custodial parent income (if applicable), which the FAFSA does not. This can significantly impact your institutional aid eligibility.
- Fees May Apply: Unlike the FAFSA, there is a fee to submit the CSS Profile, though waivers are available for eligible low-income students.
Strategic Moves to Boost Your Financial Aid by $1,500+
Beyond simply filling out forms, there are several strategic actions you can take to significantly increase your chances of receiving more financial aid. These often involve understanding how your finances are assessed and making informed decisions.
1. Manage Your Income and Assets Wisely (2024 Tax Year)
Remember, the 2026-2027 FAFSA uses your 2024 income information. This means decisions you make in the 2024 calendar year can directly impact your aid eligibility. While it’s generally not advisable to make drastic financial changes solely for financial aid, being aware of the impact can be beneficial.
- Reduce Student Income: If you are a dependent student, try to keep your income below the student income protection allowance. For the 2023-2024 academic year, this was $7,640. Income above this threshold is assessed at a higher rate (50%) than parental income. For 2026-2027, this threshold may be adjusted, so keep an eye on official FAFSA updates.
- Parental Asset Protection: Parental assets are assessed at a lower rate (up to 5.64%) than student assets (20%). If possible, move assets from the student’s name into a parent’s name. This includes savings accounts, investments, and 529 plans owned by the student. However, 529 plans owned by a parent are considered a parental asset.
- Retirement Accounts are Protected: Funds in qualified retirement accounts (401(k)s, IRAs) are not counted as assets on the FAFSA. If parents have non-retirement savings, contributing more to retirement accounts before the FAFSA base year (2024 for 2026-2027 aid) can reduce countable assets.
- Avoid Large Capital Gains: If parents are considering selling assets that would result in significant capital gains, doing so in a year that is not the FAFSA base year (i.e., after 2024 for the 2026-2027 FAFSA) can prevent a spike in reported income.
2. Appeal Your Financial Aid Package
Many students don’t realize that financial aid packages are often negotiable. If your family has experienced significant changes since the 2024 tax year – such as job loss, reduction in income, high medical expenses, or other special circumstances – you can appeal your financial aid award. This is often referred to as a ‘special circumstances’ appeal or a ‘professional judgment’ review.
- Document Everything: Gather all supporting documentation for your appeal, such as termination letters, medical bills, or pay stubs showing reduced income.
- Write a Clear Letter: Clearly explain your changed circumstances and how they impact your ability to pay for college. Be specific about the financial impact.
- Contact the Financial Aid Office: Reach out to the financial aid office at each school. They are there to help and can guide you through their specific appeal process. Don’t be afraid to ask for more. A well-justified appeal can easily lead to an extra $500, $1,000, or even more in grants or scholarships.
3. Aggressively Pursue Scholarships and Grants
Scholarships and grants are free money that doesn’t need to be repaid. While federal and institutional aid are critical, external scholarships can be the key to securing that extra $1,500 or more. The scholarship landscape is vast, with opportunities based on academics, extracurriculars, heritage, unique skills, and even obscure criteria.
- Start Early and Be Consistent: Scholarship searching should begin well before your senior year of high school and continue throughout college. Dedicate regular time each week to searching and applying.
- Utilize Scholarship Search Engines: Websites like Fastweb, Scholarship.com, Chegg Scholarships, and the College Board’s scholarship search tool are excellent starting points.
- Local Opportunities are Gold: Don’t overlook local scholarships offered by community organizations, businesses, religious groups, and high school guidance counselors. These often have fewer applicants, increasing your chances of winning.
- College-Specific Scholarships: Many colleges offer their own scholarships, often based on merit or specific departmental criteria. Check your prospective schools’ financial aid and departmental websites.
- Craft a Strong Application: Pay close attention to essay prompts, submit strong recommendation letters, and highlight your achievements and unique qualities. Tailor each application to the specific scholarship criteria.
4. Consider Work-Study Programs
Federal Work-Study (FWS) is a program that provides part-time jobs for undergraduate and graduate students with financial need, allowing them to earn money to help pay for educational expenses. While it’s not ‘free money’ in the same way a grant is, it’s a valuable form of self-help aid that reduces the need for loans.
- Indicate Interest on FAFSA: Make sure you check the box on the FAFSA indicating your interest in work-study.
- Explore On-Campus Jobs: Work-study jobs are typically on-campus or with non-profit organizations, offering flexible hours that accommodate your academic schedule.
- Gain Experience: Beyond the financial benefit, work-study jobs provide valuable work experience and can even be related to your field of study. Earning $1,500 over a semester or year through work-study is a very achievable goal.
5. Understand Your Award Letter and Negotiate
Once you receive financial aid award letters from colleges, don’t just accept the first offer. Carefully review each component of the package.
- Compare Offers: Look at the total cost of attendance versus the total ‘gift aid’ (grants and scholarships) offered. Compare loan amounts and work-study opportunities.
- Negotiate with a Better Offer: If you receive a more generous offer from one school, you can use it as leverage to ask another preferred school to match or improve their offer. This is particularly effective if the schools are comparable in terms of academic rigor or selectivity.
- Highlight Special Talents/Achievements: If you’ve had significant achievements since applying (e.g., won a national award, achieved a higher GPA), communicate these to the financial aid office. They might be able to find additional institutional scholarships.
Common Pitfalls to Avoid When Maximizing Financial Aid
Even with the best intentions, students and families can make mistakes that hinder their financial aid prospects. Being aware of these pitfalls can help you steer clear of them.
- Missing Deadlines: This is arguably the biggest mistake. Federal, state, and institutional deadlines are firm. Mark them on your calendar and set reminders.
- Inaccurate Information on FAFSA/CSS Profile: Providing incorrect information, even accidentally, can lead to delays, requests for verification, or even loss of aid. Take your time and verify every detail.
- Not Applying for Enough Scholarships: Many students apply for only a handful of scholarships. The more you apply for, the higher your chances of winning. It’s a numbers game.
- Ignoring Your College’s Financial Aid Office: These professionals are your best resource. Build a relationship with them, ask questions, and seek their guidance.
- Assuming You Won’t Qualify: Never assume your family’s income is too high for aid. Many factors go into aid calculations, and you might be surprised by what you’re eligible for, especially for institutional aid. Always apply!
- Not Understanding Loan Terms: If you do need to take out loans, understand the difference between subsidized and unsubsidized federal loans, interest rates, repayment terms, and the implications of private loans. Only borrow what you absolutely need.
The Impact of an Extra $1,500 on Your College Journey
While $1,500 might not seem like a life-changing sum in the grand scheme of college costs, its impact can be profound and far-reaching. Let’s break down what this additional funding could mean for you:
- Reduced Loan Burden: Every dollar of grant or scholarship money is a dollar you don’t have to borrow. An extra $1,500 means $1,500 less in student loan debt, which translates to less principal and interest to repay after graduation. Over the life of a typical student loan, this can save you hundreds, if not thousands, in interest payments.
- Covering Essential Expenses: Textbooks can cost hundreds of dollars per semester. An extra $1,500 could cover most, if not all, of your textbook expenses for an entire academic year, freeing up other funds. It could also cover a significant portion of your meal plan, transportation costs, or supplies.
- Financial Flexibility: Having an additional $1,500 provides a buffer for unexpected expenses. Whether it’s a sudden medical bill, a necessary repair, or an academic opportunity like a conference, having these funds can alleviate stress and allow you to focus on your studies.
- Enhanced College Experience: With less financial strain, you might have the freedom to participate in extracurricular activities, join clubs, or pursue internships that could enrich your college experience and career prospects, without worrying about how to pay for them.
- Reduced Need for Excessive Work Hours: If you’re currently working to cover expenses, an extra $1,500 could mean fewer hours spent at a part-time job, allowing more time for academics, study, and personal well-being. This can directly contribute to better academic performance and a healthier work-life balance.
The cumulative effect of maximizing your financial aid, even by incremental amounts, can significantly improve your overall college affordability and reduce post-graduation financial stress. It’s an investment of your time and effort that pays substantial dividends.
Leveraging State and Institutional Aid Programs
Beyond federal aid, state governments and individual colleges offer a wealth of financial assistance. These programs often have their own application processes and deadlines, so thorough research is essential to maximize financial aid from every possible source.
State-Specific Grants and Scholarships
Most states offer financial aid programs for residents attending in-state colleges. These can be need-based, merit-based, or tied to specific fields of study (e.g., teaching, nursing). The eligibility criteria and application processes vary widely by state.
- Check Your State’s Higher Education Agency: Every state has an agency dedicated to higher education, which provides information on state-specific grants, scholarships, and tuition assistance programs. A quick search for "[Your State] higher education financial aid" will point you in the right direction.
- Be Mindful of State Deadlines: State aid deadlines can be as early as January or February for the following academic year, often before federal deadlines. Missing these can mean missing out on significant state-funded grants.
- Residency Requirements: Ensure you meet your state’s residency requirements to qualify for state aid.
Institutional Grants and Scholarships
Colleges and universities use their own funds to provide institutional aid, which can be a substantial part of your financial aid package. This aid is often awarded based on a combination of financial need (as determined by FAFSA and/or CSS Profile) and academic merit.
- Automatic Consideration: Many institutional scholarships are awarded automatically based on your admissions application (e.g., GPA, test scores, essays). Excelling academically and presenting a strong application can increase your chances.
- Departmental Scholarships: Inquire directly with academic departments at your chosen colleges. Many departments offer scholarships to students majoring in their specific fields. These are often less competitive than general university-wide scholarships.
- Honors Programs: Acceptance into an honors program can often come with additional scholarship opportunities.
- Specific Criteria: Some institutional grants might be tied to specific criteria such as leadership, community service, artistic talent, or even unique personal circumstances. Always explore the "scholarships" section of a college’s financial aid website thoroughly.
Staying Organized and Proactive
The key to successfully navigating the financial aid process and maximizing your opportunities for 2026 is organization and proactivity. This isn’t a one-time event; it’s an ongoing process that requires attention throughout your college application and enrollment period.
- Create a Financial Aid Calendar: List all relevant deadlines for FAFSA, CSS Profile, state aid, institutional aid, and specific scholarships. Include reminders for gathering documents and submitting applications.
- Maintain a "Financial Aid" Folder: Keep all important documents organized, whether physical or digital. This includes copies of submitted applications, tax forms, award letters, and correspondence with financial aid offices.
- Track Scholarship Applications: Use a spreadsheet to keep track of the scholarships you’ve applied for, their deadlines, requirements, and your application status.
- Communicate Regularly: Don’t hesitate to reach out to financial aid officers with questions or if your financial situation changes. They are your allies in this process.
- Reapply Every Year: Remember that financial aid is typically awarded on an annual basis. You’ll need to re-file the FAFSA (and potentially the CSS Profile) every year you plan to attend college to continue receiving aid. Your eligibility may change from year to year based on income, assets, and the number of family members in college.
Beyond the First Year: Sustaining and Increasing Aid
Maximizing financial aid isn’t just about your freshman year; it’s about securing funding throughout your entire college career. Many of the strategies discussed apply every year you are enrolled.
- Maintain Academic Performance: Many scholarships and grants (especially institutional ones) require you to maintain a certain GPA or academic standing to remain eligible. Always strive for strong grades.
- Satisfactory Academic Progress (SAP): Federal financial aid requires students to maintain Satisfactory Academic Progress (SAP). This usually means completing a certain percentage of attempted credits and maintaining a minimum GPA. Failure to meet SAP can result in the loss of federal aid.
- Re-evaluate EFC/SAI Factors Annually: Your family’s financial situation can change. Be prepared to report updated income and asset information each year on the FAFSA. If there are significant changes, be ready to appeal.
- Continue Scholarship Searching: Don’t stop applying for scholarships after your freshman year. Many scholarships are available specifically for continuing college students.
- Explore Departmental Opportunities: As you progress in your major, more departmental scholarships may become available. Get to know your professors and department advisors, as they often know about these opportunities.
Conclusion: Empowering Your College Journey with Financial Preparedness
The journey through higher education is a significant investment, but it doesn’t have to be an insurmountable financial burden. By proactively engaging with the financial aid process, understanding the nuances of the FAFSA and CSS Profile, strategically managing your finances, and diligently seeking out all available resources, US college students can significantly maximize financial aid for 2026 and beyond.
Securing an extra $1,500 is not just a pipe dream; it’s an achievable goal through careful planning and persistent effort. This additional funding can provide the crucial buffer needed to cover essential expenses, reduce loan dependency, and ultimately empower you to focus more on your studies and less on financial worries. Remember, every application submitted, every deadline met, and every question asked brings you closer to a more affordable and fulfilling college experience. Take control of your financial future, and pave the way for a successful academic career.
Start today, stay organized, and don’t underestimate the power of being informed and proactive. Your future self (and your bank account) will thank you.